A community development financial institution (CDFI) is a specialized lender whose mission is to move capital into places and people that mainstream banks tend to skip. If you are a tenant group, a nonprofit, or a neighborhood organization trying to buy a building, preserve affordable units, or stand up a housing cooperative, a CDFI is often the lender that says yes when a conventional bank says the deal is too small, too unconventional, or too early. This guide explains what CDFIs are, the four types you will encounter, the federal CDFI Fund that certifies and supports them, and—most practically—how they finance affordable and cooperative housing at each stage of a project.
What a CDFI Actually Is
CDFIs are mission-driven lenders. They can be banks, credit unions, loan funds, or venture funds, but they share a legal commitment: a primary mission of promoting community development, and a defined "target market" of low-income people and underserved communities they are obligated to serve.
The category exists because of a structural gap. Conventional lenders price and approve loans based on standardized risk models. A 12-unit building owned by a newly formed tenant cooperative, a project that needs $40,000 to pay for architectural drawings before any construction loan exists, or a borrower with a thin credit file does not fit those models cleanly. CDFIs are built to underwrite exactly those situations. They combine flexible capital with hands-on technical assistance, and they measure success not only in repayment but in community impact—affordable homes preserved, ownership built, displacement avoided.
CDFIs are certified by the U.S. Department of the Treasury. Certification is not a grant of money; it is a designation confirming the institution meets the mission, target-market, accountability, and financial standards required to be recognized as a CDFI. That certification then makes the institution eligible for federal support and signals to private investors that the lender is a legitimate community development partner.
The Four Types of CDFIs
All CDFIs share the same mission, but they are structured differently and play different roles in a housing deal. Understanding the types helps you find the right partner.
Community Development Loan Funds
Loan funds are the most common type of CDFI—they make up more than half of all CDFIs. They are typically nonprofit lenders that raise capital from banks, foundations, government, and faith-based and social investors, then re-lend it on flexible terms. Loan funds are usually the most relevant CDFI for affordable and cooperative housing because they can offer the patient, higher-risk capital that early-stage projects need: predevelopment loans, acquisition loans, and bridge financing that banks rarely provide. Because they are not deposit-taking institutions, loan funds have more flexibility in how they structure and price a loan, and they often pair financing with project coaching.
Community Development Credit Unions
Credit unions are nonprofit, member-owned cooperatives that provide basic financial services—savings accounts, affordable mortgages, small-dollar loans, and credit counseling—to low- and moderate-income members. For housing cooperatives, credit unions matter on two fronts: they can be a natural ideological partner (a co-op lending to co-ops), and they can finance the individual share loans that members of a limited-equity cooperative use to buy into their unit. Their member-owned structure mirrors the governance model of a housing co-op itself.
Community Development Banks
Community development banks are federally insured depository institutions—they take deposits and make loans like any bank—but with a mission to direct lending and investment into economically distressed communities. Because they are regulated depositories, they can deploy larger pools of capital and offer the permanent ("take-out") mortgage financing that a project needs once construction is complete and units are occupied. They often work alongside loan funds: the loan fund carries the early risk, the bank provides the long-term mortgage.
Community Development Venture Capital Funds
Venture funds pool investor capital to make equity and equity-like investments in businesses that advance community and economic development goals. They are less common in straightforward housing deals than loan funds or banks, but they can be relevant for mixed-use developments, community-owned commercial space on a ground floor, or enterprises that anchor a neighborhood and create local jobs.
The CDFI Fund: The Federal Engine Behind Community Lending
The CDFI Fund, housed in the U.S. Department of the Treasury, is the federal program that certifies CDFIs and channels resources to them. Its core idea is leverage: invest federal dollars alongside private-sector capital so that every public dollar pulls in additional private and philanthropic investment. The Fund does not lend to projects directly—it strengthens the institutions that do.
Several CDFI Fund programs touch housing:
- The CDFI Program provides financial and technical assistance awards that build the capacity and lending capital of certified CDFIs.
- The Capital Magnet Fund is designed specifically to expand financing for the development, rehabilitation, and purchase of affordable housing and related community development. Awardees use the money to create financing tools—loan loss reserves, revolving loan funds, risk-sharing loans, and loan guarantees—that stretch their lending capacity. A loan loss reserve, for example, lets a CDFI absorb a degree of default risk, which in turn lets it say yes to riskier early-stage housing deals.
- The New Markets Tax Credit Program attracts private investment into low-income communities, sometimes supporting the commercial or mixed-use components of a neighborhood development.
- Bond Guarantee and related programs help CDFIs access larger-scale, longer-term capital.
The practical takeaway for a community group: the federal support a CDFI receives is part of why it can offer you terms a commercial bank cannot. You are not asking a CDFI to do you a favor—you are tapping a financing system the federal government deliberately built to fund exactly this kind of work.
How CDFIs Finance Affordable and Co-op Housing
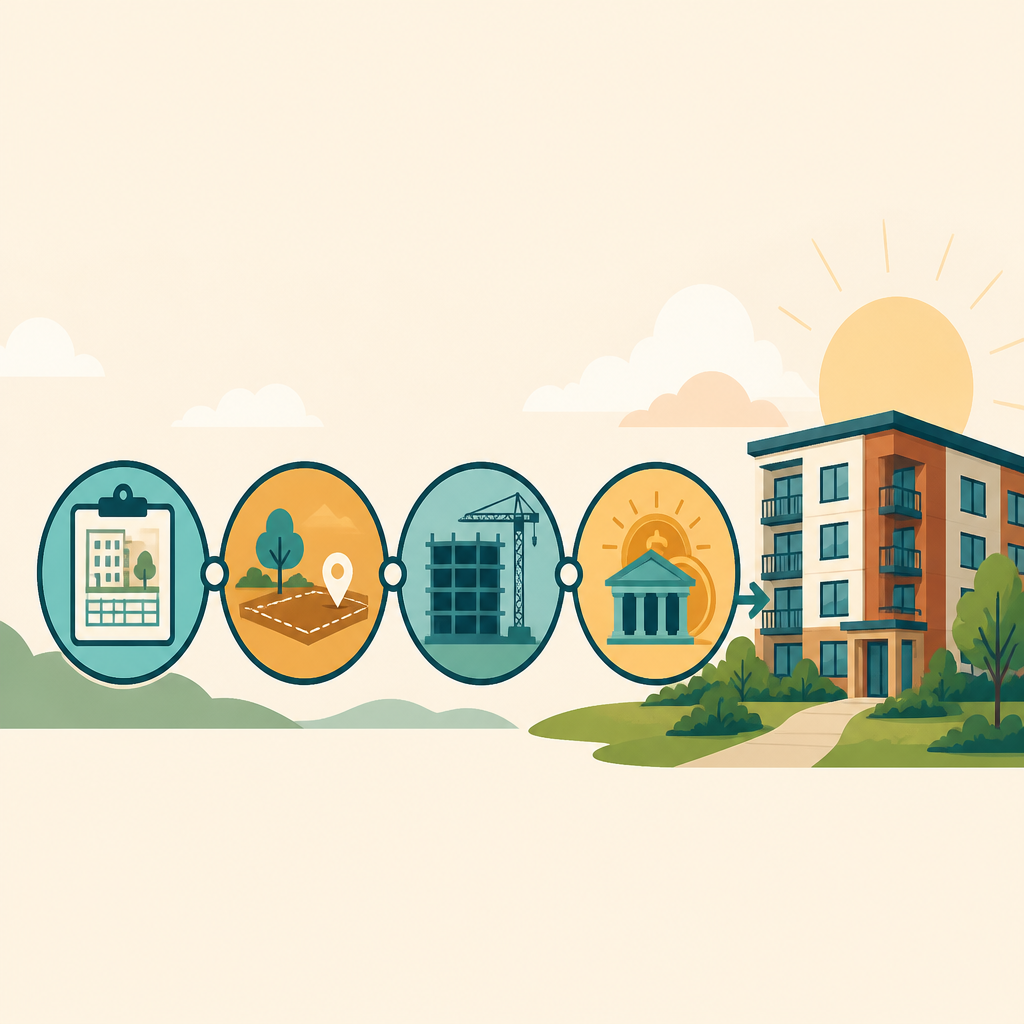
CDFIs are most valuable in the early, risky, capital-starved phases of a project—the stages where conventional financing simply is not available yet. Here is how the financing typically maps to the life of a deal.
Predevelopment Financing
Before a single permanent loan is approved, a project incurs real costs: feasibility studies, appraisals, architectural and engineering drawings, legal work to form the cooperative entity, environmental reviews, and deposits. These predevelopment costs can run into the tens or hundreds of thousands of dollars, and they come due before anyone will commit construction or permanent financing. Predevelopment loans from CDFI loan funds cover this gap. They are typically smaller, shorter-term, and carry higher risk for the lender, which is precisely why mission lenders—not banks—provide them.
Acquisition Financing
When a building comes to market, the window to buy is often short, and tenant or community buyers are competing against cash investors who can close fast. Acquisition loans let a community group or cooperative purchase the property quickly, securing site control before a slower permanent financing process is complete. For tenant groups exercising a right of first refusal or opportunity to purchase, fast, flexible acquisition capital is frequently the deciding factor between community ownership and another flip to an outside landlord.
Bridge Financing
Affordable housing deals usually stack multiple funding sources—grants, tax credits, soft public loans, philanthropic capital—and these sources rarely arrive at the same time. Bridge loans advance capital against committed-but-not-yet-disbursed funding, keeping the project moving while the slower sources catch up. Bridging committed grant or subsidy dollars is a routine, essential CDFI function that prevents a fully funded project from stalling on timing alone.
Permanent and Take-Out Financing
Once a building is acquired, rehabilitated, and occupied, the short-term loans are refinanced into a long-term permanent mortgage. Community development banks and some loan funds provide this take-out financing, often structured to keep the housing affordable over the long run.
How Community Groups Partner With CDFIs
Working with a CDFI is a relationship, not a transaction. A few principles make the partnership work:
- Engage early. Bring a CDFI in during planning, not after you have a deal under contract. They can shape the financing structure and flag problems before they become expensive.
- Come organized. A clear ownership entity, a basic development budget, and a realistic sources-and-uses plan tell the lender you are a serious, underwriteable borrower.
- Use the technical assistance. Many CDFIs pair their loans with hands-on coaching—how to structure a cooperative, build a pro forma, or sequence funding. That support is part of the value.
- Expect partnership, not just paperwork. CDFIs are mission-aligned. They want the deal to succeed and will often work with you to get there.
How Built By DAO + Blueprint Fit In
Built By DAO is a venture studio for community-owned development. Our flagship software, Blueprint, helps community groups plan, finance, and launch affordable housing cooperatives—turning the steps described above into a guided, structured process. Blueprint helps you map predevelopment, acquisition, and bridge needs, organize the financial picture a CDFI will want to see, and assemble the documentation that makes you a credible borrower.
The timing matters. The 21st Century ROAD to Housing Act (H.R.6644), passed by Congress in June 2026 (now law as of July 2026), includes Velázquez provisions that authorize cooperatives within federal housing programs—provisions aimed at a cooperative sector already home to roughly 1.5 million families. As cooperatives gain firmer federal footing, the CDFIs that finance them and the tools that help communities organize those deals become more important than ever.
Ready to plan and finance your housing cooperative? Explore Blueprint at blueprint.builtbydao.com.
Frequently Asked Questions
What is the difference between a CDFI and a regular bank?
A regular bank serves the broad market and underwrites to standardized risk models. A CDFI is a mission-driven lender legally committed to serving low-income people and underserved communities, with the flexibility to finance smaller, earlier-stage, or unconventional deals—like cooperative housing—that conventional banks typically decline.
Do CDFIs lend directly to housing cooperatives?
Yes. CDFI loan funds in particular finance cooperatives through predevelopment, acquisition, and bridge loans, while community development credit unions can finance the individual share loans members use to buy into a limited-equity co-op. The right partner depends on the stage and structure of your project.
What is the CDFI Fund?
The CDFI Fund is a U.S. Department of the Treasury program that certifies CDFIs and provides them with financial and technical assistance. Programs like the Capital Magnet Fund specifically expand financing for affordable housing. The Fund supports the institutions; the institutions finance the projects.
What are predevelopment, acquisition, and bridge loans?
Predevelopment loans cover early costs like studies, drawings, and legal work before permanent financing exists. Acquisition loans let a community group buy a property quickly. Bridge loans advance capital against committed-but-undisbursed funding so a project keeps moving. CDFIs specialize in all three.
How do I find a CDFI in my area?
The CDFI Fund maintains a list of certified institutions, and networks such as the Opportunity Finance Network can point you to mission lenders by region and focus. Many CDFIs publish the kinds of projects and borrowers they serve, so you can match your project to a lender's target market.
Does the new federal housing law change anything for co-ops?
The 21st Century ROAD to Housing Act (H.R.6644), passed by Congress in June 2026, includes Velázquez provisions that authorize cooperatives within federal housing programs and are aimed at a cooperative sector already home to roughly 1.5 million families. This strengthens the policy footing for co-ops, making CDFI financing and planning tools increasingly relevant.