Housing cooperative insurance is one of the least glamorous and most consequential decisions a co-op board makes. A cooperative is a shared asset and a shared liability: the corporation owns the building, members own shares and the right to occupy a unit, and everyone shares the financial consequences when something goes wrong. Get the coverage structure right and a fire, a slip-and-fall, or a board dispute is an inconvenience. Get it wrong and a single uncovered claim can trigger a special assessment large enough to put member households at risk.
This guide explains how risk and insurance work in a housing cooperative, how coverage is split between the corporation and individual members, and what boards can do to manage premiums that have been climbing across the property market. It is educational, not insurance advice. Every cooperative is different, and policy terms vary by carrier and state. Treat this as a framework for the conversation you should have with a licensed broker, your attorney, and your members — not as a substitute for it.
Why cooperatives have a unique risk profile
A housing cooperative is a corporation. Members don't hold a deed to real estate the way condo or single-family owners do; they own shares in the corporation and hold a proprietary lease (or occupancy agreement) for their unit. That legal structure changes who is responsible for what.
In a condominium, the association insures common areas and each owner insures their unit. In a cooperative, the corporation typically owns the entire building — structure, systems, and often the interiors — so the corporation carries far more of the insurable risk on its books. The board, acting for the corporation, makes coverage decisions that affect every household at once. That concentration of responsibility is exactly why a clear, well-documented insurance program matters so much.
The core policies a housing cooperative needs
Most cooperatives assemble several distinct coverages. The named pieces below are the ones that come up in nearly every co-op insurance review.
Master (blanket) property policy
The master policy — sometimes called a blanket property policy — is the foundation. It insures the physical building or buildings against covered perils such as fire, wind, and certain water damage, and it typically funds the cost to rebuild after a major loss. Boards face two recurring decisions here.
First, insured value. Property should generally be insured to its full replacement cost, not its market value or its outstanding mortgage balance. Underinsuring to save on premium is a classic mistake: a coinsurance clause can reduce the payout on even a partial loss if the building is insured below the required percentage of replacement cost. Many co-ops commission a periodic replacement-cost appraisal so the number stays current with construction costs.
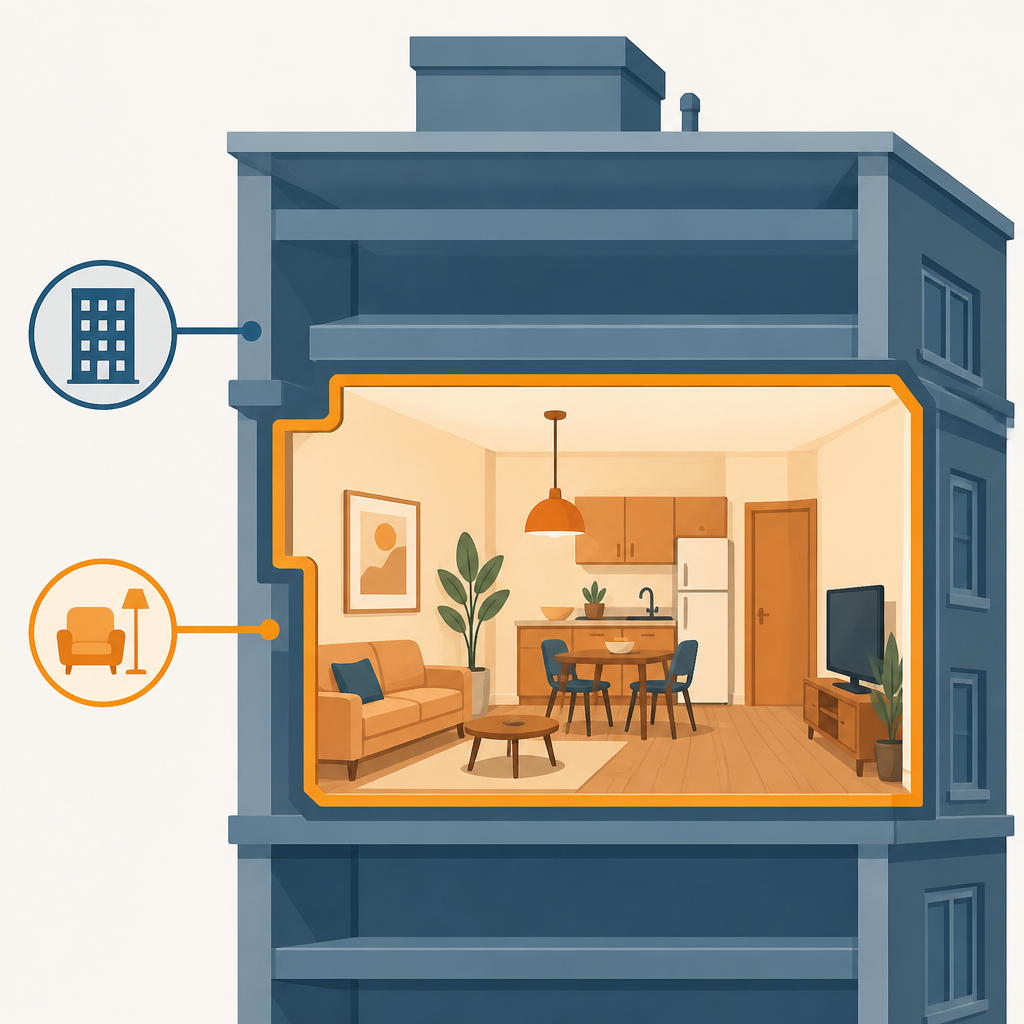
Second, the "bare walls" vs. "all-in" question. A bare-walls master policy covers the structure and common elements but stops at the unit interior, leaving fixtures, flooring, cabinetry, and improvements to the member. An all-in (or "single entity") policy extends to original unit interiors. The choice directly determines where the corporation's coverage ends and the member's begins — so it should be stated plainly in governing documents and communicated to every household.
Commercial general liability (CGL)
General liability covers third-party bodily injury and property damage claims arising from the co-op's premises and operations — the slip on an icy walkway, the visitor injured by a falling fixture, the delivery worker hurt in the lobby. Boards should pay attention to the per-occurrence and aggregate limits and consider an umbrella (excess liability) policy that sits on top of the CGL and other liability lines to extend limits for catastrophic claims. For most cooperatives, an umbrella is inexpensive relative to the protection it adds.
Directors and officers (D&O) liability
D&O insurance protects the people who serve on the board. Volunteer board members make decisions about budgets, assessments, admissions, maintenance, and rule enforcement — and any of those decisions can draw a claim from a member, an applicant, or a vendor. A good D&O policy responds to allegations of mismanagement, breach of fiduciary duty, discrimination in admissions or housing decisions, and wrongful acts in governance. Without it, individual directors can face personal exposure, and the co-op will struggle to recruit anyone willing to serve. Boards should check whether the policy covers defense costs, whether it includes employment practices and fair-housing-related claims, and how it handles claims among members and the board.
Fidelity / crime coverage (employee dishonesty)
A fidelity bond or crime policy protects the corporation's funds against theft, embezzlement, and fraud — by a board treasurer, a staff member, or a managing agent who handles co-op money. Cooperatives can hold substantial reserves and operating accounts, and the people with access are often volunteers or third parties. Coverage limits are commonly set in relation to the maximum funds on hand, including reserves, and lenders and managing-agent contracts frequently require a minimum amount. This is low-cost coverage that addresses a real and recurring loss category.
Flood insurance
Flood is excluded from standard property policies. A cooperative in or near a FEMA-designated flood zone generally needs a separate flood policy, often through the National Flood Insurance Program (NFIP) or a private flood carrier. Lenders typically require flood coverage for buildings in high-risk zones. Even outside mapped zones, boards increasingly weigh flood and water-related coverage as storm patterns shift; a large share of flood losses occur outside the highest-risk areas. Review the building's flood-zone designation, the available limits (NFIP building limits may not fully rebuild a large structure, which is where excess flood coverage comes in), and how the policy treats basements and below-grade mechanical systems.
Other coverages boards commonly evaluate
Depending on the building and operations, a co-op may also carry workers' compensation (required if the co-op has employees), boiler and machinery / equipment breakdown, non-owned and hired auto, cyber liability where the co-op stores member data online, and ordinance or law coverage, which pays the extra cost of rebuilding to current code after a loss in an older building. Ordinance-or-law in particular is easy to overlook and expensive to be without in older housing stock.
The co-op vs. member coverage line: HO-6 and the unit policy
The single most misunderstood part of cooperative insurance is the boundary between what the corporation's master policy covers and what each member must insure themselves. The master policy is not a substitute for individual coverage, and members who assume "the building is insured, so I'm covered" are usually wrong about the parts that matter most to them.
Individual members typically need a co-op unit policy — frequently written on an HO-6 form, the same form used for condos. A member's policy generally addresses:
- Personal property / contents: furniture, electronics, clothing, and belongings, which the master policy does not cover.
- Improvements and betterments: upgrades and interior finishes the member added or is responsible for, especially under a bare-walls master policy.
- Personal liability: claims arising inside the member's unit, such as a guest injured at home.
- Loss assessment coverage: a critical piece. If the corporation suffers a covered loss that exceeds its master policy limits or falls under its deductible, the board can levy a special assessment on members. Loss assessment coverage on the member's HO-6 can help pay that assessment up to the policy limit. Because master-policy deductibles have risen sharply, members are increasingly advised to carry higher loss-assessment limits.
- Loss of use / additional living expenses: temporary housing costs if the unit becomes uninhabitable.
Boards do members a real service by documenting the coverage line clearly, requiring members to carry an appropriate unit policy as a condition in the occupancy agreement, and explaining — in plain language — that the master policy's deductible can become the member's problem. The clearer the line, the fewer disputes after a loss.
Why premiums are rising — and what boards can do
Property insurance costs have increased across the market in recent years. The drivers are broad: higher rebuilding costs from construction-material and labor inflation, more frequent and severe weather events, and a tighter reinsurance market that pushes costs down to primary carriers and, eventually, to policyholders. Cooperatives feel this through higher premiums, higher deductibles, and in some regions, fewer carriers willing to quote at all.
A board can't control the market, but it can influence its own risk profile and the premium that follows. Practical risk mitigation includes:
- Maintain the building proactively. Roofs, plumbing, electrical, and heating systems are the source of most large property claims. A funded reserve and a preventive-maintenance schedule reduce both losses and the frequency of claims that drive up renewal pricing.
- Manage water aggressively. Water damage is one of the most common and costly co-op claims. Leak-detection sensors, supply-line upgrades, sump-pump maintenance, and clear shut-off procedures pay for themselves.
- Document an appraisal-based insured value. Insuring to an accurate replacement cost avoids both coinsurance penalties and the wasted premium of over-insuring.
- Right-size deductibles intentionally. A higher master-policy deductible lowers premium but shifts more risk onto the corporation and, via assessments, onto members. Pair any deductible increase with reserves and member loss-assessment coverage so the trade-off is deliberate.
- Reduce liability exposure. Lighting, snow-and-ice procedures, handrail maintenance, pool and playground rules, and contractor certificate-of-insurance requirements all lower the odds of a liability claim.
- Work with a broker who knows cooperatives. Co-op insurance is a specialty. A broker who understands master/unit coordination, loss-assessment dynamics, and lender requirements can structure a program that fits — and shop it across carriers at renewal.
- Bundle and review annually. Reviewing all coverages together each year — and getting competitive quotes — keeps gaps from opening as the building, the membership, and the market change.
None of this eliminates risk. The goal of a cooperative insurance program is to transfer the losses that would be catastrophic to the corporation or its members, retain the small ones the co-op can absorb, and prevent as many as possible through maintenance and good governance.
How Built By DAO + Blueprint fit in
Built By DAO is a venture studio for community-owned development. Our flagship platform, Blueprint, is software to plan, finance, and launch affordable housing cooperatives — and risk planning is part of building a co-op that lasts, not an afterthought bolted on at closing.
Blueprint helps founding groups and boards model the operating budget that has to carry insurance from day one: master-policy premiums, deductible reserves, D&O and fidelity coverage, and the loss-assessment exposure members share. By making these costs visible during planning and financing — rather than at the first renewal shock — Blueprint helps cooperatives set realistic budgets, fund reserves, and document the coverage line before members move in.
This momentum is reinforced by policy. The 21st Century ROAD to Housing Act (H.R.6644), passed by Congress in June 2026 (now law as of July 2026), includes the Velázquez provisions that authorize cooperatives in federal housing programs — a cooperative sector already home to roughly 1.5 million families. As cooperatives expand under that framework, sound insurance and risk management become essential to keeping these homes stable and affordable.
Ready to plan a cooperative built to last? Explore Blueprint at blueprint.builtbydao.com.
Frequently asked questions
Does the co-op's master policy cover my belongings?
Generally, no. The master (blanket) property policy insures the building and, depending on whether it is "bare walls" or "all-in," some or all of the unit interior. It does not cover your personal belongings, and it may not cover improvements you made. That's what an individual co-op unit policy (often an HO-6) is for. Confirm the specifics with your board and a licensed agent.
Do individual members really need their own insurance?
In almost every case, yes — and many cooperatives require it in the occupancy agreement. A member's unit policy covers personal property, personal liability, additional living expenses, improvements you're responsible for, and loss assessment, which can help pay a special assessment if a corporation-level loss exceeds the master policy's limits or falls under its deductible.
What is loss assessment coverage, and why does it matter more now?
Loss assessment coverage on a member's HO-6 helps pay special assessments the corporation levies after a covered loss — often to cover the master-policy deductible. As deductibles have risen, the potential out-of-pocket cost to members has grown, so brokers increasingly recommend higher loss-assessment limits. It is usually an inexpensive add-on relative to the exposure.
Why does a volunteer board need D&O insurance?
Because board decisions — on budgets, assessments, admissions, and rule enforcement — can draw claims of mismanagement, breach of fiduciary duty, or discrimination. D&O liability insurance covers defense costs and damages so individual directors aren't personally exposed. Without it, recruiting members willing to serve becomes much harder.
How can a cooperative lower its insurance costs?
Boards can't change the market, but they can lower their own risk: insure to an appraisal-based replacement value, maintain building systems proactively, manage water risk, set deductibles deliberately alongside adequate reserves, reduce liability hazards, and work with a broker who specializes in cooperatives and shops the program at each renewal.
Does my cooperative need flood insurance?
If the building is in a FEMA-designated high-risk flood zone, lenders generally require it, and standard property policies exclude flood. Even outside high-risk zones, many losses occur where flood risk is considered moderate or low, so boards increasingly evaluate flood and excess-flood coverage as part of an overall risk review.
This article is educational and does not constitute insurance, legal, or financial advice. Coverage terms, requirements, and availability vary by carrier, state, and individual cooperative. Consult a licensed insurance broker and your attorney before making decisions about your cooperative's insurance program.