Every housing cooperative eventually faces the same operational question: who keeps the buildings running, the books balanced, and the members served? Strong housing cooperative property management is the difference between a co-op that builds equity and stability for its members and one that drifts into deferred maintenance, surprise assessments, and conflict. The choice usually comes down to two paths—managing the property yourselves or hiring a professional management company—and most co-ops land somewhere on a spectrum between the two.
This guide walks through what property management actually covers in a cooperative, how self-management compares to hiring a firm, what these services cost, how boards keep managers accountable, and how to choose a manager who genuinely understands the co-op model. The goal is to help your board make a deliberate decision rather than defaulting into one by accident.
What "Property Management" Means in a Co-op
In a housing cooperative, members collectively own the corporation that owns the building, and each member holds a share or membership that comes with the right to occupy a unit. That ownership structure changes what management means. A property manager for a rental building answers to a landlord and tenants. A property manager for a co-op answers to a member-owned board and serves member-owners who are also their own landlords. The relationship is closer to running a small mutual organization than collecting rent.
The scope of services typically spans several domains:
Financial management
This is often the most important function. It includes collecting monthly carrying charges (the co-op equivalent of rent plus a share of operating costs), paying vendors and the underlying mortgage, managing the operating account and reserve account, producing monthly financial statements, supporting the annual audit, and helping the board build and track the budget. In limited-equity and affordable cooperatives, financial management also means staying compliant with the rules attached to public financing or subsidies.
Administrative and member services
Processing membership applications and share transfers, maintaining the waitlist, handling move-ins and move-outs, enforcing house rules and occupancy agreements, responding to member questions, keeping corporate records, and supporting board and membership meetings. Good administration keeps the cooperative legally sound and keeps members informed.
Physical operations and maintenance
Routine maintenance, custodial work, grounds and snow, responding to repair requests, coordinating emergency repairs, scheduling inspections, and overseeing on-site staff if the co-op employs any. This is the visible face of management—the part members notice every day.
Compliance and reporting
Insurance renewals, regulatory filings, fair housing compliance, lender and agency reporting, and meeting any requirements tied to federal, state, or local housing programs. Cooperatives that participate in public programs carry meaningful reporting obligations, and this load is poised to grow as more programs open to co-ops.
Self-Management vs. a Professional Management Company
There is no universally correct answer. The right choice depends on the co-op's size, complexity, finances, and the capacity of its members.
The case for self-management
Self-managed cooperatives handle operations through their own board, committees, and sometimes a paid employee or two. The appeal is real:
- Cost savings. You avoid a management fee, which can free up meaningful budget—often money that goes straight back into reserves or keeps carrying charges lower.
- Control and responsiveness. Decisions don't route through an outside firm. Members who care deeply about their home can act on that care directly.
- Member engagement. Running the co-op builds skills, ownership, and community. Many cooperators consider this a feature, not a burden.
Self-management works best for smaller co-ops, buildings with simple systems, and communities with members who have relevant skills—accounting, trades, legal, administration—and the time to use them. The risks are equally real: burnout, key-person dependency (the one member who knows how everything works), uneven enforcement of rules among neighbors, and gaps in specialized knowledge like reserve studies or compliance. A self-managed co-op often still hires professionals à la carte: a bookkeeper, an accountant for the audit, attorneys, and contractors.
The case for a professional management company
A management company brings systems, staff, and experience that a volunteer board can't easily replicate. Advantages include:
- Expertise and continuity. Firms know housing law, accounting standards, vendor markets, and compliance. They don't quit because they moved or got tired.
- Bandwidth. Day-to-day operations stop depending on volunteers, which protects against burnout and turnover.
- Professional distance. A manager can enforce rules and collect arrears without the strain of doing it to your own neighbor.
- Buying power and vendor networks. Established firms often secure better pricing and have trusted contractors on call.
The trade-offs: cost, and the risk of a manager who treats your co-op like just another account. A firm built for conventional rentals may not understand member-ownership, the carrying-charge model, or the governance rhythms of a board. Choosing the wrong company can be worse than self-managing.
The hybrid reality
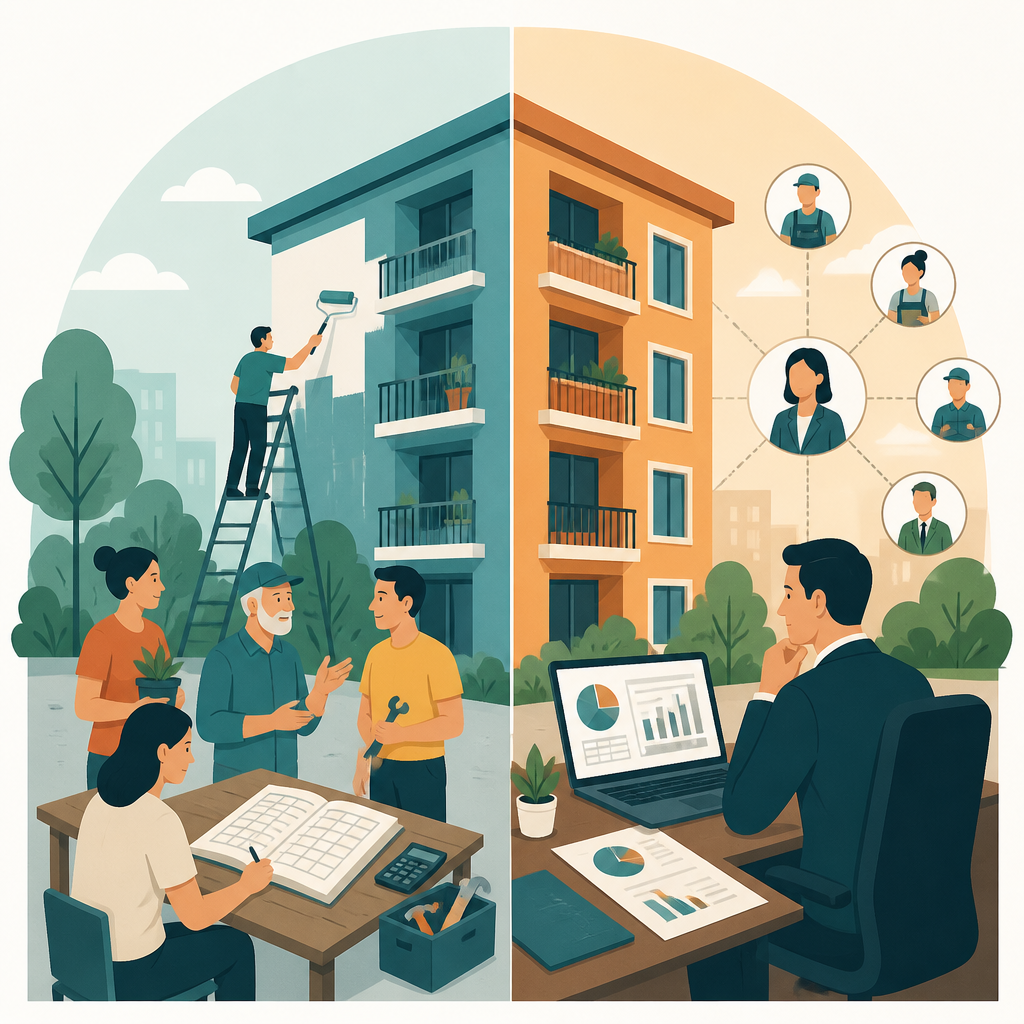
Most cooperatives operate in between. A common arrangement is professional management for finance, compliance, and administration, paired with on-site staff or member committees handling day-to-day maintenance and community life. Another is self-management with a part-time managing agent or a fee-for-service consultant who handles only the technical work. Treat self-manage-or-hire as a spectrum, not a switch.
Maintenance and Capital Planning
Maintenance breaks into two categories, and conflating them is one of the most common—and expensive—co-op mistakes.
Routine and corrective maintenance is the day-to-day: fixing leaks, servicing boilers, replacing fixtures, keeping common areas clean and safe. It's funded from the operating budget. Whether self-managed or professionally managed, the co-op needs a reliable system for logging requests, dispatching the right person, and tracking that work gets done.
Capital planning is the long game—roofs, elevators, boilers, facades, parking lots, major mechanical systems. These items fail predictably over decades and cost far more than any single month's budget can absorb. The discipline that protects a co-op here is the reserve study: a professional assessment of major components, their remaining useful life, replacement cost, and the funding schedule needed to pay for them. A funded reserve account, fed by a line item in every budget, lets the co-op replace a roof without a special assessment that members can't afford.
A capable property manager—or a disciplined self-managing board—commissions reserve studies periodically, updates them, and holds the line on reserve contributions even when it's tempting to keep carrying charges artificially low. Underfunded reserves are the single most common cause of co-op financial distress. For affordable and limited-equity cooperatives, where the entire point is durable affordability, capital planning isn't optional bookkeeping; it's mission protection.
Vendor Management
Cooperatives rely on a roster of vendors: plumbers, electricians, HVAC and elevator contractors, landscapers, insurers, accountants, and attorneys. Managing them well means:
- Competitive bidding for significant work, with multiple written bids and clear scopes so you're comparing equivalents.
- Vetting—licensing, insurance, references, and a track record with similar buildings.
- Written contracts with defined scope, price, timeline, and warranty terms.
- Performance tracking so chronic underperformers get replaced and good vendors get retained.
- Conflict-of-interest safeguards, especially when a member or board member has a stake in a vendor. Disclose, recuse, and document.
A management company typically brings an existing vendor network and handles procurement, but the board should still set bidding thresholds and approval requirements. Self-managing co-ops build this network themselves, which takes time but yields deep local relationships and full transparency into pricing.
What It Costs
Management fees vary by region, building size, and scope, so treat any figure as a starting point to verify locally rather than a quote. Companies commonly charge either a per-unit, per-month fee or a percentage of the operating budget, sometimes with a minimum monthly fee for small properties. Smaller co-ops usually pay more per unit because fixed costs spread across fewer units.
Watch for what the base fee does and doesn't include. Common add-ons billed separately: share transfers and resales, special projects and capital project oversight, after-hours emergency response, legal coordination, and extra reporting. Ask for a complete fee schedule in writing before signing.
When weighing cost, compare honestly. Self-management isn't free—you'll still pay for bookkeeping, accounting, legal help, and possibly staff, and you'll spend volunteer hours that have real value. The right comparison is total cost and total risk under each model, not "fee versus zero."
Board Oversight of Management
Hiring a manager does not transfer responsibility. The board remains legally and fiduciarily accountable to the membership; the manager is an agent acting under the board's direction. Effective oversight includes:
- A clear management agreement spelling out scope, fees, term, reporting cadence, spending authority, and termination rights. Spending limits matter: define what the manager can approve alone versus what needs board sign-off.
- Regular reporting. Monthly financials, maintenance and arrears summaries, and updates on open projects—reviewed, not just received.
- Defined decision rights. The board sets policy, budgets, and major decisions; the manager executes. Blurring this line is where co-ops lose control.
- Annual performance review against the agreement, with renewal tied to results.
- Direct access to records. The co-op owns its books, contracts, and member data. Insist on access and on clean handoff if you ever change managers.
A manager who resists transparency or treats the board as a rubber stamp is a warning sign, no matter how polished the operation looks.
Choosing a Manager Experienced With Co-ops
If you go professional, co-op experience is the deciding factor. Managing a cooperative differs from managing rentals in ways that trip up generalist firms—carrying charges instead of rent, share transfers instead of leases, member governance instead of a single owner, and program compliance for affordable co-ops. Screen for it:
- Ask for a co-op portfolio—how many cooperatives they manage and for how long. References from co-op boards, not just landlords.
- Probe the affordable/limited-equity track record if that's your structure, including experience with the relevant public programs and their reporting.
- Test their governance fluency. Do they understand the difference between board direction and management execution? Can they support, not steamroll, member democracy?
- Review reporting samples so you know what you'll actually receive each month.
- Confirm capital and reserve experience—reserve studies, capital projects, and long-term planning, not just collecting carrying charges.
- Check fit and culture. A co-op is a community. The manager who serves it well respects that.
The wrong manager can quietly erode the member-ownership that makes a cooperative worth living in. The right one strengthens it.
How Built By DAO + Blueprint Fit In
Most management guidance assumes the co-op already exists. Built By DAO works upstream—we're a venture studio for community-owned development, and our flagship platform, Blueprint, helps groups plan, finance, and launch affordable housing cooperatives in the first place.
That early-stage work is where good property management begins. Blueprint helps founding groups model realistic operating budgets, size reserve contributions from day one, and structure the cooperative so that whether you self-manage or hire, the financial foundation supports durable affordability. Decisions made during planning—carrying-charge levels, reserve funding, governance structure—shape how manageable the co-op will be for decades.
The timing matters. With the 21st Century ROAD to Housing Act (H.R.6644) passed by Congress in June 2026 (now law as of July 2026), the Velázquez provisions authorize cooperatives within federal housing programs—a cooperative sector already home to roughly 1.5 million families. As more co-ops form under these provisions, the demand for sound operations and management will only grow. Building the operational foundation right from the start is the best protection your members have.
If you're forming a cooperative—or strengthening one—explore how Blueprint can help you plan finances and operations that last.
Frequently Asked Questions
Can a small housing cooperative manage itself?
Yes. Many small co-ops self-manage successfully, especially when they have members with relevant skills and the time to contribute, and when they still hire specialists—a bookkeeper, an accountant for the annual audit, and attorneys—for technical work. The keys are avoiding key-person dependency and keeping financial discipline, particularly on reserves.
How much does a property management company charge a co-op?
Fees vary widely by region, building size, and scope, and are usually structured as a per-unit monthly fee or a percentage of the operating budget, often with a minimum for small properties. Smaller co-ops typically pay more per unit. Always request a full written fee schedule, including which services cost extra, before signing. Verify current local rates rather than relying on national averages.
What's the most important thing a co-op manager does?
For most cooperatives, financial management—accurate accounting, collecting carrying charges, paying obligations, funding reserves, and supporting the budget and audit. Healthy finances and a funded reserve account are what keep a co-op stable and affordable over the long term.
Does hiring a manager mean the board gives up control?
No. The board stays legally and fiduciarily responsible and directs the manager, who acts as its agent. A clear management agreement, defined spending limits, regular reporting, and annual performance reviews keep the board in control while the manager handles day-to-day execution.
What is a reserve study and why does it matter?
A reserve study is a professional assessment of a building's major components—roof, boiler, elevators, facade—estimating their remaining life, replacement cost, and the funding needed to pay for them on schedule. It lets a co-op fund major replacements gradually instead of hitting members with unaffordable special assessments. Underfunded reserves are a leading cause of co-op financial trouble.
How do I find a manager who understands cooperatives?
Look specifically for co-op experience, not just rental management. Ask for a portfolio of cooperatives, references from co-op boards, evidence they understand member governance and carrying charges, and—if you're an affordable or limited-equity co-op—a track record with the relevant public programs and their compliance requirements.