Learning how to buy into a housing cooperative is different from buying a standard house or condo, and that difference trips up many first-time buyers. When you join a co-op, you are not buying real estate in the conventional sense. You are buying a membership share in a corporation that owns the building, and that share gives you the right to occupy a specific unit. This structure changes how you finance the purchase, how you get approved, and what your ongoing responsibilities look like. This guide walks through the entire process — from finding a co-op to closing and settling in as a member — so you know what to expect at each step.
What a Housing Cooperative Actually Is
A housing cooperative is a corporation owned collectively by the people who live in it. Instead of holding a deed to a unit, each member owns shares in the cooperative and holds a proprietary lease (sometimes called an occupancy agreement) that grants the right to live in a particular home. Decisions about the building — budgets, repairs, rules, and who gets to join — are made democratically, typically on a one-member-one-vote basis regardless of unit size.
There are a few common models, and the differences matter for buyers:
Market-Rate Co-ops
Shares are bought and sold at whatever the market will bear. When you sell, you keep the appreciation. These are common in cities like New York and behave more like traditional homeownership in terms of resale value.
Limited-Equity Co-ops
A resale formula caps how much you can sell your share for, which keeps units permanently affordable for the next buyer. You build modest equity rather than market-rate wealth, but your monthly costs stay low and predictable. Most affordable housing cooperatives use this model.
Zero-Equity and Leasing Co-ops
Members pay a low or nominal buy-in and the cooperative prioritizes affordability over equity-building. These often serve very low-income households or operate on leased land or in community land trusts.
Knowing which model a co-op uses tells you most of what you need to know about cost, resale, and who the community is built to serve.
Step 1: Find the Right Co-op
Co-op listings do not always appear where you expect. Some show up on the same portals as other homes for sale, but many — especially limited-equity and mission-driven co-ops — are advertised through local housing nonprofits, community land trusts, city housing agencies, and word of mouth.
When searching, focus on:
- Affordability model. Confirm whether it is market-rate or limited-equity before you fall in love with a unit.
- Income eligibility. Many affordable co-ops set maximum (and sometimes minimum) income limits tied to Area Median Income (AMI).
- Location and waitlists. Established affordable co-ops frequently have waitlists. Get on them early.
- Financial health. A low share price means nothing if the building carries heavy debt or a thin reserve fund. You will dig into this in Step 4.
Talk to current members if you can. They will tell you more about how the community actually functions than any listing.
Step 2: Understand How You'll Pay — Share Loans and Financing
Because you are buying shares rather than real property, you typically cannot use a standard mortgage. Instead, buyers use a share loan (also called a co-op loan). A share loan is secured by your shares and proprietary lease rather than by a recorded mortgage on real estate.
Key things to know about financing a co-op purchase:
Not Every Lender Offers Share Loans
Share loans are a specialty product. Credit unions, community development financial institutions (CDFIs), and certain regional banks are more likely to offer them than large national lenders. Mission-driven lenders often specialize in financing limited-equity and affordable co-ops.
Down Payment and Underwriting
You will still be underwritten on credit, income, and debt-to-income ratio, much like a mortgage. Down payment requirements vary by co-op and lender, and some affordable co-ops have low buy-in amounts that you may be able to pay without a loan at all.
The Co-op Must Approve the Loan
Cooperatives frequently set their own financing rules — maximum loan-to-value ratios, minimum down payments, and which lenders they will work with. Confirm the co-op's lending requirements before you apply, so you are not approved by a lender the building won't accept.
Two Monthly Costs to Budget For
After closing, you will pay (1) your share loan payment, if you took one, and (2) a monthly carrying charge (also called maintenance) to the cooperative. The carrying charge covers your share of the building's underlying mortgage, property taxes, insurance, utilities, staff, and reserve contributions. Ask for the current carrying charge and the history of increases over the past several years.
Step 3: The Application and Board Interview
This is the step that surprises traditional buyers most. In nearly every co-op, the board of directors must approve you as a member before you can buy in. The board's job is to protect the financial stability and community of the building, so expect a thorough process.
The Application Package
You will typically submit a detailed package that may include:
- Financial statements, tax returns, and pay stubs or proof of income
- Bank and asset statements
- Credit report and employment verification
- Reference letters (personal and sometimes professional)
- A completed co-op application and, for income-restricted co-ops, income documentation proving eligibility
The Board Interview
After your package is reviewed, you will usually be invited to an interview with the board or a membership committee. This is part financial due diligence and part "are you a good fit for the community" conversation. Be honest, be prepared to explain your finances, and ask your own questions about how the co-op operates. For affordable and limited-equity co-ops, the interview often emphasizes your willingness to participate in the cooperative — attending meetings, serving on committees, and sharing responsibility for the building.
Approval and Fair Housing
Boards have wide discretion, but they cannot discriminate on the basis of protected characteristics under fair housing law. If something feels off, you are entitled to ask about the criteria being applied. A well-run co-op will have clear, consistent membership standards.
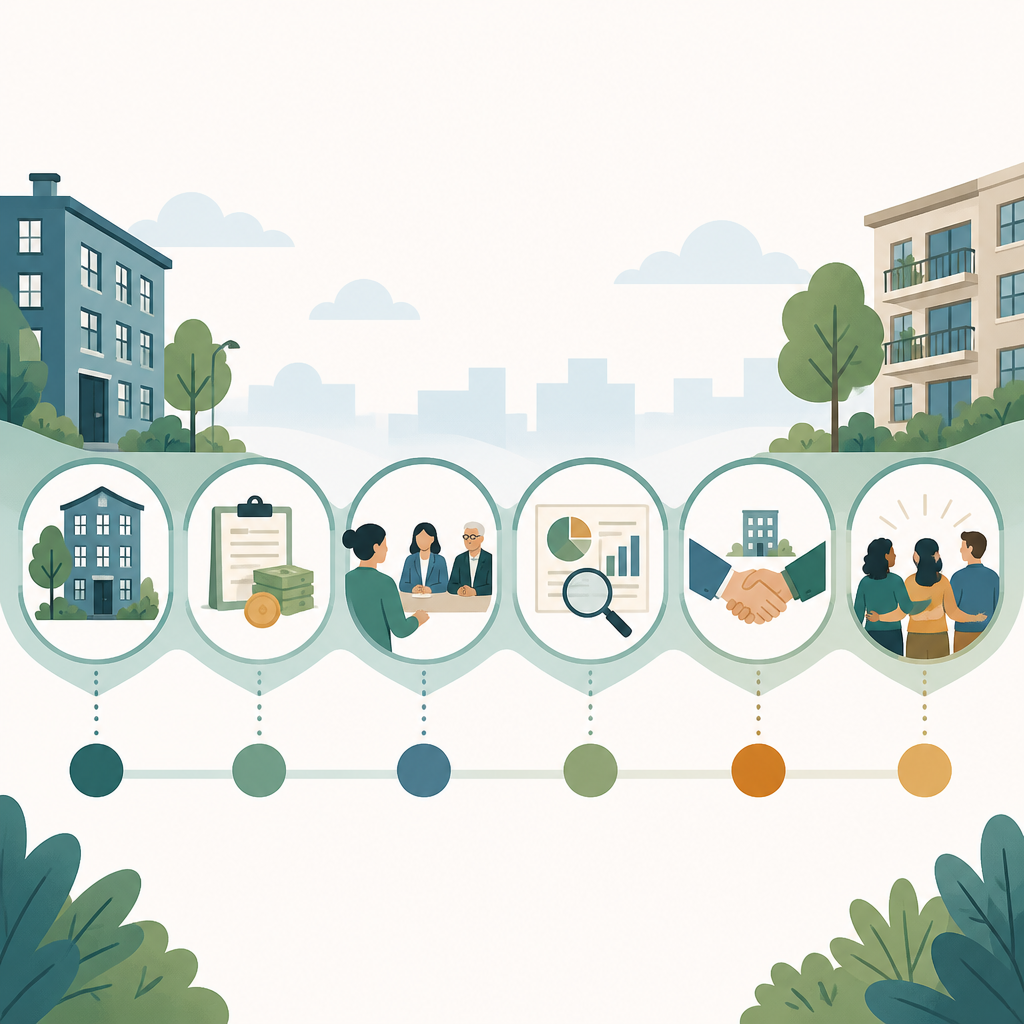
Step 4: Review the Financials and Bylaws
Before you commit, you must understand the financial and legal health of the cooperative. Treat this with the same seriousness you would a home inspection. Many buyers bring in an attorney or accountant experienced with co-ops to help review these documents.
Documents to Request and Read
- Bylaws and proprietary lease/occupancy agreement — your rights, the rules, subletting and resale restrictions, and how decisions get made.
- Audited financial statements — at least the past two to three years.
- The current operating budget — to see how carrying charges are spent.
- The underlying mortgage details — the building's blanket loan balance, rate, and maturity. This affects everyone's carrying charges.
- Reserve fund balance — money set aside for major repairs. A healthy reserve protects you from sudden assessments.
- Board meeting minutes — to spot looming repairs, disputes, or planned increases.
- Move-in and resale policies — especially the resale formula in a limited-equity co-op, so you know exactly what you can sell for later.
Red Flags
Watch for chronic operating deficits, a depleted reserve fund, a large balloon payment coming due on the underlying mortgage, frequent special assessments, or high vacancy and arrears. Any of these can mean future cost increases.
Step 5: Closing
Co-op closings are generally simpler than a traditional real estate closing because no deed is transferred. Instead, you receive a stock certificate (your shares) and the proprietary lease.
At closing you can expect to:
- Sign the proprietary lease and acknowledge the bylaws and house rules
- Receive your stock certificate evidencing your shares
- Pay the purchase price, any closing costs, and applicable fees (some co-ops charge a flip tax or transfer fee)
- Finalize your share loan, if you have one, including any required recognition agreement between the lender, the co-op, and you
- Set up your monthly carrying charge payments
Closing costs are usually lower than for a house purchase, but confirm the specifics in writing beforehand so there are no surprises.
Step 6: What to Expect as a Member
Once you close, you are not just a homeowner — you are a co-owner of the whole building and a participant in how it runs.
- Monthly carrying charges. Pay on time; these fund the building's operations, and arrears affect everyone.
- Democratic governance. You get a vote in elections and major decisions. Members elect the board, which handles day-to-day governance.
- Participation. Especially in affordable co-ops, expect to attend meetings and ideally serve on a committee. Engaged membership is what keeps costs low and the community strong.
- Rules and approvals. Renovations, subletting, pets, and selling your unit often require board approval. Read the rules so you know what is and isn't allowed.
- Responsibility for the whole. When the roof needs replacing, members share the cost. That shared responsibility is also what gives you real control over your housing.
The trade-off is the heart of cooperative living: a little less individual autonomy in exchange for stability, affordability, and genuine community ownership.
Why Housing Cooperatives Matter Right Now
Cooperatives are getting renewed attention as a tool for permanently affordable housing. In June 2026, the 21st Century ROAD to Housing Act (H.R. 6644) was passed by Congress and became law that July. The bill includes provisions championed by Representative Nydia Velázquez that authorize housing cooperatives within federal housing programs — provisions aimed at a cooperative sector already home to roughly 1.5 million families. For buyers, this signals a growing ecosystem of programs, lenders, and co-ops to choose from in the years ahead, especially in the affordable and limited-equity space.
How Built By DAO + Blueprint Fit In
Built By DAO is a venture studio focused on community-owned development. Across our brands — Urban Array, and Running Start Digital, founded by Marquis Davis — we build tools and ventures that put ownership in the hands of communities rather than distant landlords.
Our flagship product, Blueprint, is software that helps groups plan, finance, and launch affordable housing cooperatives. If you have searched for a co-op to buy into and come up short, that scarcity is the real problem — there simply aren't enough cooperatives yet. Blueprint exists to change that by making it dramatically easier for organizers, nonprofits, and resident groups to stand up new co-ops with sound financials and clear governance from day one.
If you want to help create the next generation of affordable housing cooperatives — or you're part of a group ready to form one — explore Blueprint.
Frequently Asked Questions
Is buying into a housing cooperative cheaper than buying a house?
It often has lower upfront and monthly costs, especially in limited-equity co-ops, because you buy shares rather than real estate and share the building's expenses. But in market-rate co-ops, prices can rival condos. Always compare the share price plus carrying charges against the alternatives.
Can I get a regular mortgage for a co-op?
Usually not. Co-op buyers typically use a share loan secured by their shares and proprietary lease rather than a standard mortgage. Credit unions, CDFIs, and some regional banks specialize in these loans, and the co-op must approve your financing.
Why does the board have to approve me?
The cooperative is collectively owned, so existing members vet new buyers to protect the building's financial stability and community. Boards can set membership and financial standards, but they cannot discriminate based on characteristics protected under fair housing law.
What's the difference between a market-rate and a limited-equity co-op?
In a market-rate co-op, you can resell your shares for whatever the market allows and keep the appreciation. In a limited-equity co-op, a resale formula caps your sale price to keep the unit affordable for the next buyer — you trade large equity gains for low, stable housing costs.
What documents should I review before buying?
At minimum: the bylaws and proprietary lease, two to three years of audited financials, the operating budget, the underlying mortgage details, the reserve fund balance, recent board minutes, and the resale policy. Consider hiring an attorney or accountant experienced with co-ops.
What ongoing costs will I have as a member?
You'll pay a monthly carrying charge (covering your share of the building's mortgage, taxes, insurance, utilities, and reserves) and, if you financed the purchase, your share loan payment. Budget for occasional special assessments for major repairs.