If you want to know how to start a housing cooperative, you are asking one of the most important questions in housing right now. A housing cooperative lets a group of residents collectively own and govern the building or community they live in, replacing a landlord with a member-owned corporation. The result is housing that stays affordable, decisions that stay local, and equity that stays with the community instead of flowing out to outside investors.
This guide walks through the full process: deciding whether a co-op is right for your group, forming the legal entity, financing the acquisition or development, and launching member operations. It is written for residents, organizers, nonprofit developers, and community leaders who want a clear, non-hype roadmap rather than a sales pitch.
The timing matters. In June 2026, Congress passed the 21st Century ROAD to Housing Act (H.R. 6644) (now law as of July 2026) — described as the largest housing affordability measure in a generation. Provisions backed by Congresswoman Nydia Velázquez explicitly authorize housing cooperatives as eligible participants in federal housing programs, fixing vague statutory language that had left co-ops at risk of exclusion. For the roughly 1.5 million families already living in co-ops nationwide, and for the communities considering one, that is a meaningful tailwind.
What Is a Housing Cooperative?
A housing cooperative is a corporation owned and democratically controlled by the people who live in it. Instead of buying a deed to a specific unit, you buy a membership share in the corporation, which gives you the right to occupy a home and one vote in governance — typically one vote per household, regardless of unit size or share price.
There are three common structures:
- Limited-equity cooperative (LEC): Resale prices are capped by formula so homes stay permanently affordable. This is the model most often used for affordable, community-owned housing and the one Urban Array and Built By DAO focus on.
- Market-rate cooperative: Shares can be resold at market value. Members build wealth like homeowners but affordability is not protected over time.
- Mutual housing association / zero-equity: Residents control the property collectively but do not hold transferable equity shares; affordability is maximized.
For affordability-focused groups, the limited-equity model strikes the balance most people are looking for: residents build modest, real equity while the homes remain reachable for the next generation of members.
Before You Start: Is a Co-op the Right Fit?
A co-op is not the right tool for every situation. It works best when:
- You have a committed core group of at least a handful of households willing to govern together.
- Members value long-term affordability and shared control over maximum individual resale profit.
- There is a property to acquire (or land to develop) and a realistic path to financing.
- The group is prepared to handle ongoing governance, maintenance, and shared financial responsibility.
If your group wants quick individual ownership with no shared obligations, a co-op will feel like friction. If your group wants durable, affordable, community-controlled housing, it is one of the strongest vehicles available.
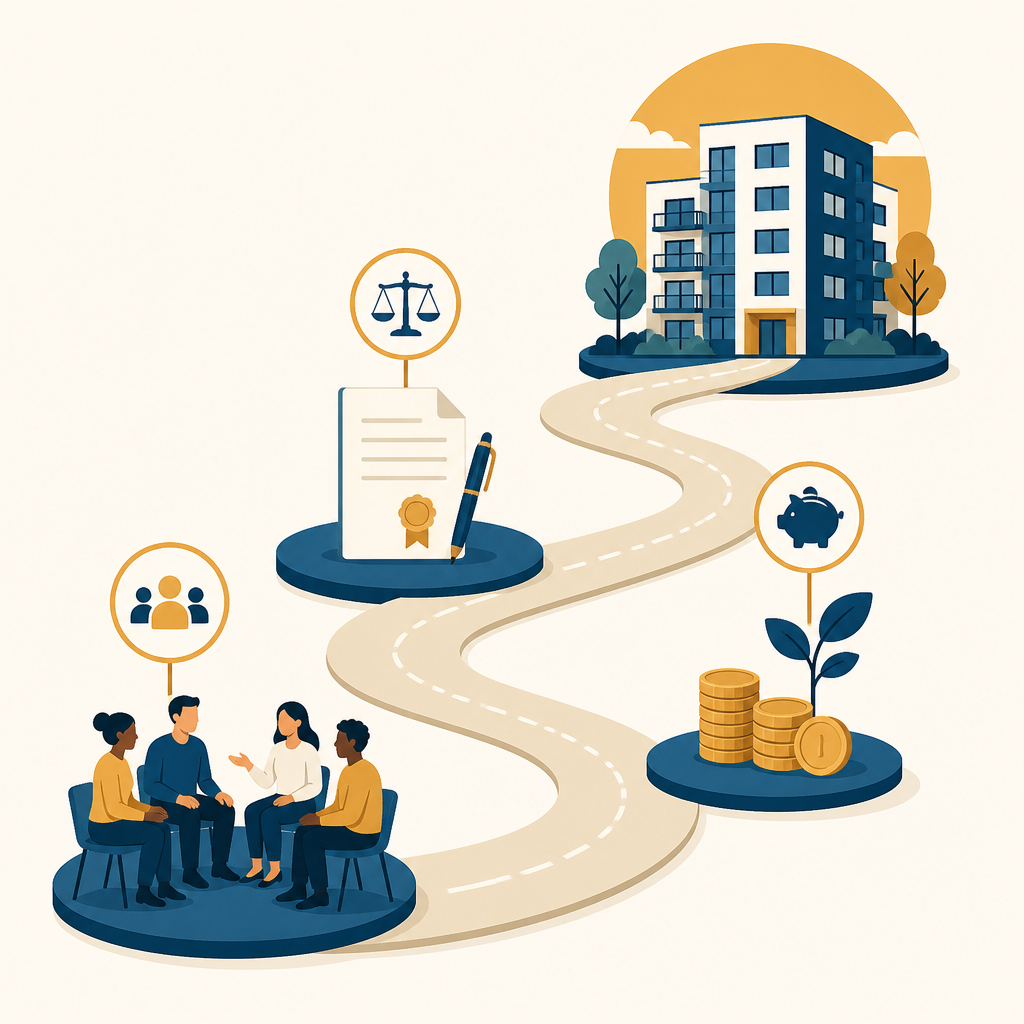
How to Start a Housing Cooperative: 9 Steps
Below is the core sequence. Real projects rarely move in a perfectly straight line — financing and legal formation often overlap — but this is the order most successful cooperatives follow.
1. Build and organize your founding group
Recruit a committed core of prospective members. Hold open meetings, agree on shared goals, and establish a steering committee. Decide early whether you are pursuing limited-equity (permanent affordability) or market-rate, because nearly every later decision flows from that choice. Document who is in, what each household can contribute, and how decisions will be made during the formation phase.
2. Define your mission and membership criteria
Write a short mission statement and draft basic membership requirements: who is eligible, how members are admitted, and what the expected share purchase and monthly carrying charge will be. Clear, fair, written criteria protect the group from disputes later and are required by most lenders and public funders.
3. Incorporate the cooperative
Form a legal entity — usually a cooperative corporation or, in some states, an LLC or nonprofit structured to operate cooperatively. File articles of incorporation with your state and obtain an EIN. The entity, not any individual, will hold title to the property and the underlying mortgage. Engaging an attorney experienced in cooperative or affordable-housing law at this stage prevents costly fixes later.
4. Draft bylaws, the occupancy agreement, and the subscription agreement
These three documents are the legal backbone of the co-op:
- Bylaws govern voting, board elections, meetings, and member rights and responsibilities.
- Occupancy (proprietary lease) agreement gives each member the right to occupy a home and sets the monthly carrying charge.
- Subscription agreement governs the purchase of membership shares.
For a limited-equity co-op, this is also where you write the resale formula that caps share appreciation and keeps homes affordable across generations.
5. Identify and assess the property
Whether you are converting an existing rental building, buying a vacant property, or developing new construction, commission a realistic assessment: inspection, appraisal, environmental review, and a capital-needs estimate for repairs and reserves. Underestimating deferred maintenance is one of the most common reasons new co-ops struggle financially.
6. Build the development and operating budget
Two budgets matter. The development budget covers acquisition, rehab or construction, and soft costs (legal, appraisal, organizing). The operating budget projects monthly carrying charges against expenses: the blanket mortgage, taxes, insurance, utilities, management, maintenance, and — critically — reserve contributions. Carrying charges must cover real costs, or the co-op will face special assessments down the road.
7. Secure financing
Cooperatives typically use a blanket mortgage held by the corporation, sometimes layered with public subsidy, soft loans from community development financial institutions (CDFIs), grants, or a seller carryback. Members contribute share purchases as the equity layer. Federal programs are increasingly relevant here: the 2026 ROAD to Housing Act's explicit authorization of cooperatives in federal housing programs is designed to make co-ops cleanly eligible for financing tools they were previously at risk of being excluded from. Pair public and mission-driven capital with a lender that genuinely understands co-op underwriting.
8. Recruit and admit members; close the deal
Finalize your membership roster, collect share payments, and coordinate the closing with your attorney, lender, and any public funders. At closing, the cooperative corporation takes title and the blanket financing is put in place. Each admitted household signs its subscription and occupancy agreements.
9. Launch governance and operations
Elect your first board, adopt house rules, set up bookkeeping and reserve accounts, and establish a maintenance plan. Decide whether you will self-manage or hire a professional manager experienced with cooperatives. Strong onboarding for new members — explaining rights, responsibilities, and the budget — is what turns a legal entity into a functioning, durable community.
Common Challenges (and How to Plan for Them)
- Financing complexity: Co-op underwriting is specialized. Start lender conversations early and line up technical assistance.
- Governance fatigue: Democratic control requires participation. Build realistic committees and rotate responsibilities.
- Underfunded reserves: Set carrying charges to fund reserves from day one, not after the first emergency.
- Documentation gaps: Bylaws, occupancy agreements, and resale formulas must be airtight. Do not use generic templates without legal review.
Most of these are solvable with good planning and the right tools — which is exactly the gap Built By DAO set out to close.
How Built By DAO + Blueprint Fit In
Built By DAO is a venture studio for community-owned development. Our cooperative housing arm, Urban Array, develops and deploys limited-equity cooperatives in historically disinvested communities — working through the steps above on real buildings in real neighborhoods. We are living this process now, which is why we built software to make it repeatable.
Blueprint is our platform for planning, financing, and launching affordable housing cooperatives. It helps founding groups model development and operating budgets, structure financing layers, generate the governance and membership framework, and move a project from a committed group of neighbors to a closed deal. It is built to operationalize exactly the model the 2026 ROAD to Housing Act now explicitly validates at the federal level.
If you are serious about starting a co-op, you do not have to assemble the roadmap, the spreadsheets, and the legal scaffolding from scratch.
Plan, finance, and launch your housing cooperative with Blueprint → blueprint.builtbydao.com
Frequently Asked Questions
How much money do I need to start a housing cooperative?
It varies widely with property cost, condition, and available subsidy. Individual members typically contribute a share purchase as equity, while the corporation carries a blanket mortgage for the bulk of acquisition and rehab. Limited-equity co-ops are specifically designed to keep both the share price and monthly carrying charges affordable, often with help from public funds, CDFIs, and grants.
How long does it take to form a housing cooperative?
For a straightforward conversion with an organized group and available financing, expect roughly several months to a year. New construction or complex acquisitions can take longer. The biggest variables are financing, legal formation, and how quickly your group reaches consensus.
What is the difference between a limited-equity and market-rate co-op?
In a limited-equity cooperative, resale prices are capped by a formula so homes remain affordable for future members — you build modest equity but not market-rate windfalls. In a market-rate co-op, shares resell at market value, building more individual wealth but losing long-term affordability protection.
Do I own my home in a housing cooperative?
You own a membership share in the cooperative corporation, which grants you the right to occupy your home and a vote in governance. You do not hold a separate deed to your individual unit; the corporation holds title to the entire property. In practice, members enjoy long-term security of tenure similar to ownership.
How does the 2026 ROAD to Housing Act affect housing cooperatives?
The 21st Century ROAD to Housing Act (H.R. 6644), passed by Congress in June 2026, includes provisions that explicitly authorize housing cooperatives as eligible participants in federal housing programs. This fixes previously vague statutory language that had put co-ops at risk of exclusion, making it easier for cooperatives to access federal financing and support.
Can a renting community convert an existing building into a co-op?
Yes. Tenant-led conversions of existing rental buildings into limited-equity cooperatives are one of the most common and powerful paths to community ownership. The process follows the same steps — organize, incorporate, finance, and acquire — with special attention to the building's condition and reserve needs.