A Section 8 housing cooperative arrangement pairs a federal Housing Choice Voucher with membership in a housing co-op, so that a household's monthly subsidy helps cover the cost of cooperative occupancy or ownership rather than a conventional landlord's rent. For families who want the stability of resident-controlled housing but cannot carry the full monthly cost on their own, this pairing can be the difference between renting indefinitely and holding a permanent, equity-style stake in where they live.
This is an educational overview, not official program guidance. Housing Choice Voucher rules are administered by HUD and by local Public Housing Authorities (PHAs), and the specifics vary by agency. Always confirm details with your PHA and a qualified housing counselor before relying on any of the concepts below.
What a housing cooperative is (and why vouchers fit)
A housing cooperative is a corporation owned and governed by the people who live in it. Instead of renting a unit from an outside owner, a household buys a membership share in the cooperative corporation and signs an occupancy agreement (sometimes called a proprietary lease) that gives them the right to live in a specific unit. The cooperative as a whole owns or finances the building; members collectively control it through an elected board and one-member-one-vote governance.
Members do not pay "rent" in the ordinary sense. They pay a monthly carrying charge — their proportional share of the cooperative's operating costs: the underlying mortgage (the "blanket loan"), property taxes, insurance, utilities, maintenance, reserves, and management. Because the co-op is nonprofit at the entity level and members share costs at scale, carrying charges are often lower than comparable market rent.
Two structural features make cooperatives a natural fit for voucher assistance:
- The monthly charge looks economically like rent. A carrying charge is a recurring, occupancy-based payment, which is the kind of cost a Housing Choice Voucher is designed to offset.
- Co-ops serve income-eligible households at scale. Cooperatives in the United States house roughly 1.5 million families, including a large share in limited-equity cooperatives (LECs) specifically created to keep housing affordable long-term.
The challenge has historically been administrative clarity: voucher programs were built around the landlord-tenant model, and co-ops do not always map cleanly onto it. That ambiguity is exactly what recent federal legislation set out to reduce.
How Housing Choice Vouchers interact with co-ops
There are two broad ways a voucher and a cooperative can come together. Understanding the difference is essential, because the rules, paperwork, and outcomes are not the same.
1. The rental (tenant-based or project-based) path
In the rental model, the cooperative is treated like a housing provider, and the member is treated like a tenant for voucher purposes. The PHA pays a Housing Assistance Payment (HAP) that covers the gap between what the household can afford (generally about 30% of adjusted monthly income) and the approved carrying charge, up to the PHA's payment standard.
This path is most straightforward when:
- The household occupies a unit but does not (or cannot yet) purchase a full ownership share, or holds a nominal/limited share, and
- The cooperative is willing to enter into a HAP contract and meet program requirements such as Housing Quality Standards inspections and rent (carrying-charge) reasonableness.
In this arrangement the voucher subsidizes occupancy. The member gets the governance and stability benefits of co-op living, while the assistance functions much like it would in a private rental.
2. The Housing Choice Voucher homeownership option
HUD's homeownership voucher option lets a PHA, at its discretion, use voucher assistance to help an eligible household with the monthly costs of owning a home rather than renting one. Under longstanding HUD rules, the homeownership option can apply to a cooperative membership — meaning a co-op share purchase can qualify as the "home" being bought.
When a co-op is treated under the homeownership option, the voucher can help cover monthly homeownership-style expenses, which for a cooperative member can include the share of the cooperative's debt service, operating costs, and other carrying charges attributable to the unit. Eligibility typically requires the household to meet PHA homeownership-program criteria, which historically have included items such as:
- Being a first-time homeowner (with defined exceptions),
- A minimum income requirement and, often, an employment requirement,
- Completing pre-purchase homeownership counseling, and
- Operating under the PHA's adopted homeownership program (not every PHA runs one).
The homeownership option is permissive, not mandatory — a PHA chooses whether to offer it and how to design it. That discretion is why two families in different cities can have very different experiences trying to pair a voucher with a co-op.
Carrying-charge subsidy concepts you need to understand
The phrase "carrying-charge subsidy" describes the core mechanic that makes a Section 8 housing cooperative pairing work. A few concepts make it concrete.
The carrying charge is the subsidized cost. Whether the voucher runs through the rental path or the homeownership option, the underlying expense being offset is the member's monthly carrying charge. The PHA establishes whether that charge is reasonable and which portion is eligible for assistance.
Affordability is still pegged to income. As in standard voucher programs, the household's own contribution is generally calibrated around 30% of adjusted monthly income. The subsidy fills the gap between that contribution and the recognized monthly cost, subject to the PHA's payment standard and program rules.
Limited-equity co-ops amplify the benefit. In a limited-equity cooperative, resale prices for membership shares are capped by formula, which keeps both the buy-in and ongoing carrying charges low and durably affordable. Pairing a voucher with an LEC stacks two affordability mechanisms: the structural cap on cost and the monthly subsidy. The result can be deeply affordable, resident-controlled housing that stays affordable for the next member, too.
Equity and term may be limited by design. Households should understand that a limited-equity share is not the same as market-rate homeownership. The trade-off — capped appreciation in exchange for permanent affordability and lower entry costs — is intentional and is part of why these models work for federal subsidy.
How the 21st Century ROAD to Housing Act helps
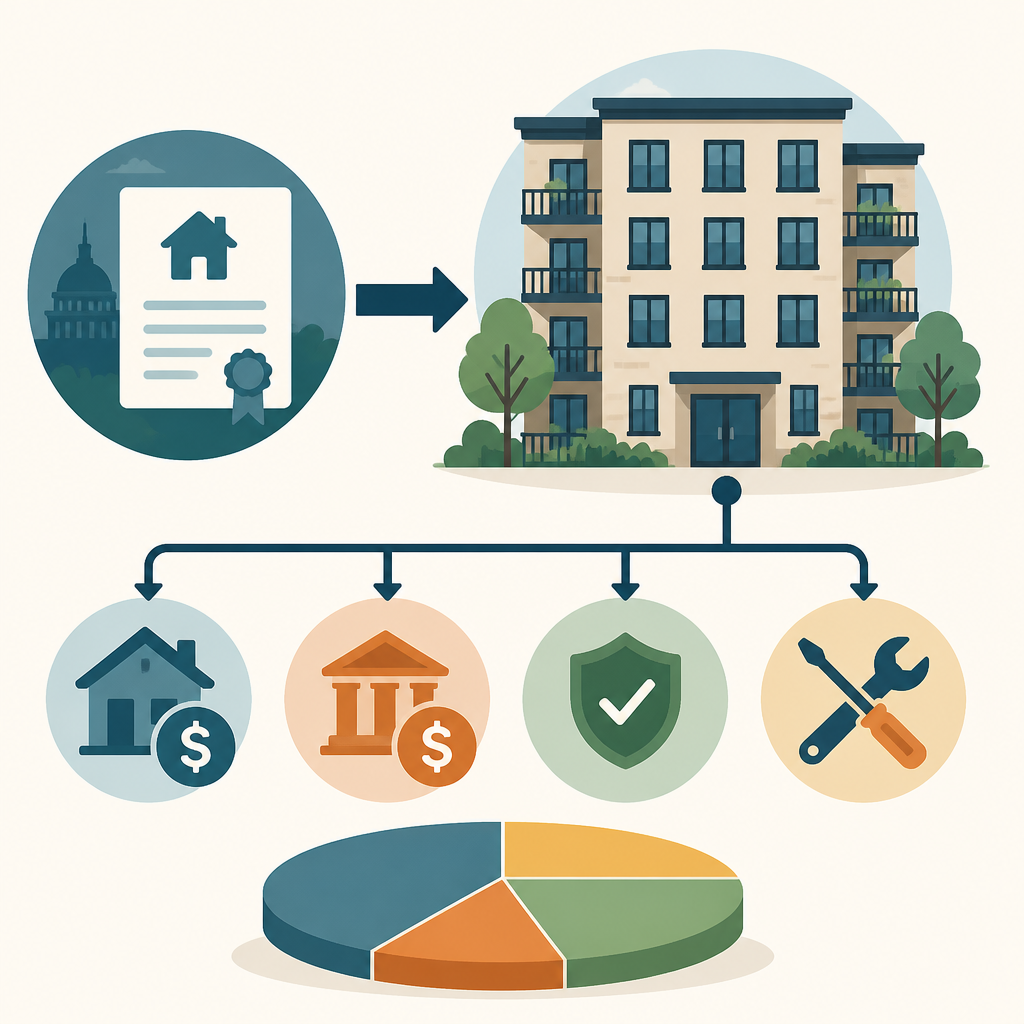
The 21st Century ROAD to Housing Act (H.R. 6644), became law in July 2026, is the most significant housing affordability law since 1990. Among its many provisions, the Velázquez measures are directly relevant here: they explicitly authorize housing cooperatives as eligible participants in federal housing programs.
That eligibility language matters because, for years, the friction in pairing vouchers with co-ops was rarely about policy intent — it was about ambiguity. Program rules written around the landlord-tenant relationship left PHAs, lenders, and cooperatives uncertain about how a co-op share, an occupancy agreement, and a carrying charge fit the federal framework. Uncertainty is expensive: it slows approvals, discourages PHAs from running co-op-friendly homeownership programs, and makes cooperatives hesitant to enter HAP contracts.
By naming cooperatives as eligible participants, the bill helps in several practical ways:
- It reduces interpretive risk. Clear statutory eligibility gives PHAs firmer footing to pair Housing Choice Vouchers — including under the homeownership option — with cooperative ownership and occupancy.
- It legitimizes the carrying-charge model. Recognizing co-ops as program participants supports treating the carrying charge as a subsidizable housing cost.
- It strengthens the case for new co-ops. When developers and communities know voucher pairing is on firmer ground, building or converting to cooperative ownership becomes a more financeable, more attractive option.
The law does not, by itself, hand any individual family a voucher or force a PHA to run a homeownership program. Local discretion and program design still govern. But it removes a major structural obstacle and signals that cooperatives are a recognized part of the federal affordable-housing toolkit.
How Built By DAO + Blueprint fit in
Built By DAO is a venture studio for community-owned development. Through our ecosystem — including Urban Array, which builds cooperative housing in disinvested communities — we focus on turning policy openings like the ROAD to Housing Act into real, financed, resident-owned homes.
Our flagship platform, Blueprint, is software to plan, finance, and launch affordable housing cooperatives. For groups exploring a Section 8 housing cooperative model, Blueprint helps with the parts that usually stall projects: modeling carrying charges, structuring limited-equity share pricing, mapping where voucher assistance can offset member costs, and assembling the financial picture a PHA, lender, or counselor will want to see. It is built to make the cooperative path legible to the same institutions that administer federal housing programs.
If you are a community group, developer, or housing organization thinking about pairing vouchers with cooperative ownership, explore the tools and start planning at blueprint.builtbydao.com.
Frequently asked questions
Can you use a Section 8 voucher in a housing cooperative?
In many cases, yes. A voucher can be paired with a cooperative either by treating the co-op as a housing provider under the rental model, or through HUD's homeownership voucher option, which can apply to a cooperative membership. Whether and how it works depends on your local Public Housing Authority's program design, so confirm with your PHA before counting on it.
What is the difference between the rental path and the homeownership voucher?
Under the rental path, the member is treated like a tenant and the PHA pays a Housing Assistance Payment toward the carrying charge. Under the homeownership voucher option, the household is treated as buying the co-op share, and assistance offsets monthly homeownership-style costs. The homeownership option is optional for each PHA and usually carries additional requirements such as counseling and income or employment thresholds.
What is a carrying charge, and is it the same as rent?
A carrying charge is a cooperative member's monthly share of the co-op's operating and financing costs — mortgage, taxes, insurance, maintenance, utilities, and reserves. Economically it functions like rent, which is why voucher assistance can be used to offset it, but legally it reflects membership in a member-owned corporation rather than a landlord-tenant lease.
How does the 21st Century ROAD to Housing Act change things for co-ops?
The Act's Velázquez provisions explicitly authorize housing cooperatives as eligible participants in federal housing programs. That clarity reduces the legal ambiguity that previously made PHAs and cooperatives cautious about pairing vouchers with co-op ownership and occupancy. It does not guarantee any specific family a voucher, but it strengthens the foundation for these pairings.
What is a limited-equity cooperative, and why does it matter for vouchers?
A limited-equity cooperative caps the resale price of membership shares by formula, keeping both buy-in costs and carrying charges low and permanently affordable. When you pair a voucher with a limited-equity co-op, you combine a structural affordability mechanism with a monthly subsidy, which can make resident-controlled housing accessible to households that could not otherwise afford to buy.
Where can I get official guidance on voucher use in cooperatives?
Start with your local Public Housing Authority, which administers Housing Choice Vouchers and decides whether to run a homeownership program. HUD publishes the governing rules for the voucher and homeownership programs, and a HUD-approved housing counseling agency can walk you through eligibility. This article is educational and is not a substitute for that official guidance.